Find a Medicare Part D prescription drug plan
Medicare Part D
Prescription Drug Coverage 2026
Medicare Part D Plans 2026
Shopping for next year? Enrollment for 2027 coverage runs from October 15 to December 7,
Curious about the changes coming to Medicare Part D Plans
You’ll see higher deductibles, new out-of-pocket limits, and better catastrophic coverage. These updates, driven by the Inflation Reduction Act, aim to make medications more affordable and accessible. Read on to find out everything you need to know.
Key Takeaways
In 2026 , the standard initial deductible for Medicare Part D will increase to $615, while the out-of-pocket spending limit rises to $2,100, impacting beneficiaries’ costs during the coverage phases.- The Inflation Reduction Act introduces critical updates, including a $35 cap on monthly insulin costs, expanded vaccine coverage, and a drug price negotiation program aiming to reduce expenses for high-cost medications.
- Enrollment in Medicare Advantage plans is on the rise, with more than half of eligible beneficiaries participating, driven by benefits such as lower costs and integrated services compared to standalone Prescription Drug Plans.
Overview of Medicare Part D Plans for 2026
Medicare Part D plans are evolving to better serve beneficiaries
Additionally, beneficiaries will see adjustments in their out-of-pocket spending limits and enhanced coverage during the catastrophic phase. These changes are influenced by the Inflation Reduction Act, which aims to lower prescription drug costs and provide enhanced benefits for enrollees.
The following sections will break down these updates in more detail.
Standard Initial Deductible Increase
This deductible adjustment aims to balance program sustainability with quality drug coverage standards.
Out-of-Pocket Spending Limit Adjustment
The out-of-pocket spending limit for Medicare Part D will rise to $2,100
This new out-of-pocket spending cap will take effect on January 1,
Catastrophic Coverage Phase Benefits
Starting January 1, 2024, Medicare beneficiaries will benefit from zero cost-sharing for formulary drugs during the Catastrophic Coverage phase. This significant change means that once enrollees reach the catastrophic threshold, they will not have to pay out-of-pocket for covered formulary medications, enhancing the Part D benefit and easing the financial burden on those with high prescription drug costs.
Key Updates Under the Inflation Reduction Act
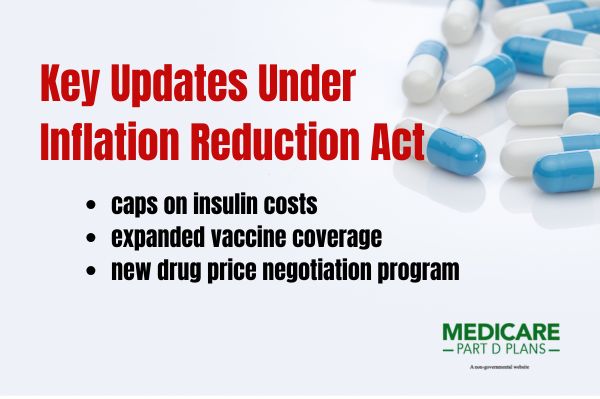
The Inflation Reduction Act brings several key updates to Medicare Part D
The Inflation Reduction Act targets high prescription drug costs and expands covered services to positively impact Medicare beneficiaries. The following subsections will provide detailed insights into these crucial updates.
Insulin Cost Cap
One of the most impactful changes under the Inflation Reduction Act is the introduction of a cap on insulin costs. Starting
This cap applies to both Part D and Part B coverage, ensuring comprehensive support for insulin users across the Medicare program.
Expanded Vaccine Coverage
Medicare Part D’s expanded vaccine coverage will include additional vaccines such as those for shingles and whooping cough starting
Drug Price Negotiations
The Medicare drug price negotiation program aims to lower costs for select high-cost drugs starting
However, the program faces legal challenges, with several lawsuits questioning its constitutionality. Despite these hurdles, the negotiation program represents a significant step towards reducing prescription drug costs and improving the financial well-being of Medicare beneficiaries.
See plans in your area instantly!
Advertisement
Enhanced Risk Adjustment Model for Part D
The enhanced risk adjustment model for Medicare Part D began phasing in
The model balances potential gains and losses for Part D sponsors, which helps stabilize premiums for beneficiaries. The goal is to keep the Medicare program sustainable without pricing enrollees out of drug coverage.
Multiple Linear Regression Methodology
CMS uses a multiple linear regression methodology to calculate normalization factors for risk adjustment in the Part D model. The approach integrates five years of historical fee-for-service risk scores, which improves the accuracy and fairness of payments across the Medicare Part D program.
Impact on Premiums and Payments
A second protection caps how much any single plan can raise its total Part D premium year over year. That cap is $50
The Premium Stabilization Demonstration Is Ending
CMS announced on July 28,
This matters for anyone enrolled in a standalone Prescription Drug Plan. The $10 monthly subsidy and the $50 increase cap both disappear after
If you are in a standalone drug plan, compare your options during the Annual Enrollment Period rather than letting your plan renew automatically. Plans that leaned heavily on the subsidy are the most likely to reprice.
Revised Risk Corridors
Revised risk corridors remain a key part of the risk adjustment model and improve the predictability of costs for Medicare Part D plans. They limit how much a sponsor can gain or lose relative to its bid, which reduces the incentive to price defensively and keeps premiums closer to actual expected cost.
Low-Income Subsidy (LIS) Program Adjustments
The Low-Income Subsidy, also called Extra Help, is the program that makes Medicare Part D affordable for people with limited income and resources. It can cover your drug plan premium, eliminate your deductible, and cut your copays to a few dollars per prescription.
Extra Help is unaffected by the demonstration ending, so if you qualify, your costs
Eligibility Criteria
To qualify for the full Low-Income Subsidy
Alaska and Hawaii use higher thresholds. Income counted toward the limit also reflects a $20 monthly disregard, so you may still qualify even if your gross income looks slightly over the line. Apply through Social Security rather than assuming you are ineligible.
Resource Limits
Resources also count.
Countable resources include bank accounts, stocks and bonds. They do not include your home, your car, personal belongings, or a burial plot. A significant number of people who would qualify never apply because they assume their savings disqualify them.
Medicare Advantage and Part D Integration
Medicare Advantage plans that build in Part D drug coverage continue to gain ground. More than half of the eligible Medicare population is now enrolled in Medicare Advantage, reflecting a shift toward plans that bundle hospital, medical and prescription coverage into a single package rather than pairing Original Medicare with a separate drug plan.
Integration often means lower total costs and extra benefits such as dental and vision. It also means a narrower network and a single plan controlling both your medical and drug coverage, which is the tradeoff to weigh.
MA-PDs vs. Standalone PDPs
Medicare Advantage Prescription Drug plans (MA-PDs) often carry lower overall costs than standalone Prescription Drug Plans, and many are available with a $0 plan premium. They typically add benefits a standalone drug plan cannot offer, such as dental and vision coverage.
Standalone PDPs remain the right choice if you want to keep Original Medicare, or if you carry a Medicare Supplement policy and need drug coverage alongside it. With the premium stabilization subsidy ending after
Find a Plan and Enroll Online Yourself!
Advertisement
Enrollment Trends
Enrollment in Medicare Advantage plans has been steadily increasing, with 32.8 million individuals enrolled by 2024, accounting for 54% of the eligible Medicare population. This trend is expected to continue, with projections indicating that 64% of Medicare beneficiaries will choose Medicare Advantage plans by 2034.
The robust market offering approximately 43 plans per beneficiary reflects this growth.
When the 2026 Part D Changes Took Effect
Every
There is no coverage gap to worry about. The donut hole was eliminated in 2025, and once your out-of-pocket spending reaches $2,100 you pay nothing more for covered drugs for the rest of the calendar year.
Medicare Part D Prescription Coverage Made Simple
Finding the right Medicare Part D plan doesn’t have to be confusing. Get coverage for your medications and avoid high out-of-pocket costs next year.
Our licensed agents can help you compare options and choose a plan that fits your prescriptions perfectly.
Call 1-866-930-4039 now to review your
Frequently Asked Questions
-
What is the standard Initial Deductible for Medicare Part D
in 2026 ?
The standard Initial Deductible for Medicare Part D
-
What is the out-of-pocket spending limit (RxMOOP) for Medicare Part D
in 2026 ?
The annual out-of-pocket spending limit for Medicare Part D
-
What change occurred to the Initial Coverage Limit (ICL) in 2025?
The Initial Coverage Limit (ICL) was eliminated in 2025 and replaced by the annual drug maximum out-of-pocket spending limit (RxMOOP). This change gives you more predictable out-of-pocket costs for prescription drugs.
-
Can I still spread my Medicare Part D costs across the year?
Yes. The Medicare Prescription Payment Plan lets you spread your out-of-pocket drug costs into capped monthly payments across the calendar year instead of paying large amounts at the pharmacy counter. Participation is voluntary and you must opt in through your Part D plan.
-
What methodology is used for the Part D risk adjustment model?
The Part D risk adjustment model uses a multiple linear regression methodology to determine normalization factors, integrating five years of historical fee-for-service risk scores to improve accuracy.
Begin Choosing your plan
Advertisement
ZRN Health & Financial Services, LLC, a Texas limited liability company.