Compare Medicare Part D prescription drug plans in your area
Medicare Part D
Prescription Drug Coverage 2026
Medicare Part D Plan Comparison
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 12,
A Medicare Part D plan comparison comes down to one question: which plan covers every drug you take at the lowest total cost for the year? Premiums are only part of the answer. The deductible, the tier each of your drugs sits on, and the pharmacy you use decide what you actually pay. This guide walks through each of those, step by step, so you can compare plans on the numbers that matter.
⚑2027 Medicare Part D plans are now available
Enrollment for 2027 plans runs October 15 to December 7,
Key Takeaways
- Part D comes two ways: a standalone Prescription Drug Plan (PDP) alongside Original Medicare, or a Medicare Advantage plan with drug coverage built in (MA-PD).
- Compare plans on total annual cost for your own drug list: premium, deductible, and copays together. The cheapest premium is often not the cheapest plan.
- The coverage gap, or donut hole, was eliminated in 2025. Once you reach the annual out-of-pocket cap, covered drugs cost you nothing for the rest of the year.
- Formulary tier and pharmacy choice can change the price of the same drug by hundreds of dollars a year.
- You can switch plans every year during the Annual Enrollment Period, October 15 to December 7.
Understanding Medicare Part D
Medicare Part D is the part of Medicare that pays for outpatient prescription drugs. Original Medicare, Parts A and B, does not cover most medications you pick up at a pharmacy, so Part D fills that gap. Plans are sold by private insurance companies that Medicare approves, which is why premiums, covered drugs and pharmacy prices differ from one plan to the next.
Even if you take no prescriptions today, it usually pays to enroll when you first become eligible. Going without Part D or other creditable drug coverage adds a late enrollment penalty that stays on your premium for as long as you have Medicare. Learn more about what Medicare Part D is and how it works.
PDP vs. MA-PD: The Two Types of Part D Plans
The first comparison you make is not between two plans. It is between two kinds of plan. Which one fits depends on whether you want to keep Original Medicare or move to a Medicare Advantage plan.
| Standalone drug plan (PDP) | Medicare Advantage with drugs (MA-PD) | |
|---|---|---|
| Works with | Original Medicare (Parts A and B) | Replaces how you receive Parts A and B |
| Covers | Prescription drugs only | Hospital, medical and drugs in one plan |
| Premium | Separate monthly premium on top of Part B | Often a $0 plan premium; you still pay Part B |
| Doctor network | None for medical care | Usually an HMO or PPO network |
| Works with Medigap | Yes, and needed, since Medigap does not cover drugs | No, you cannot hold both |
Watch out before you switch
If you have a Medicare Advantage plan with drug coverage and you enroll in a standalone Part D plan, Medicare will disenroll you from the Advantage plan and return you to Original Medicare. Check which type you have before you enroll in anything.
The Four Costs to Compare
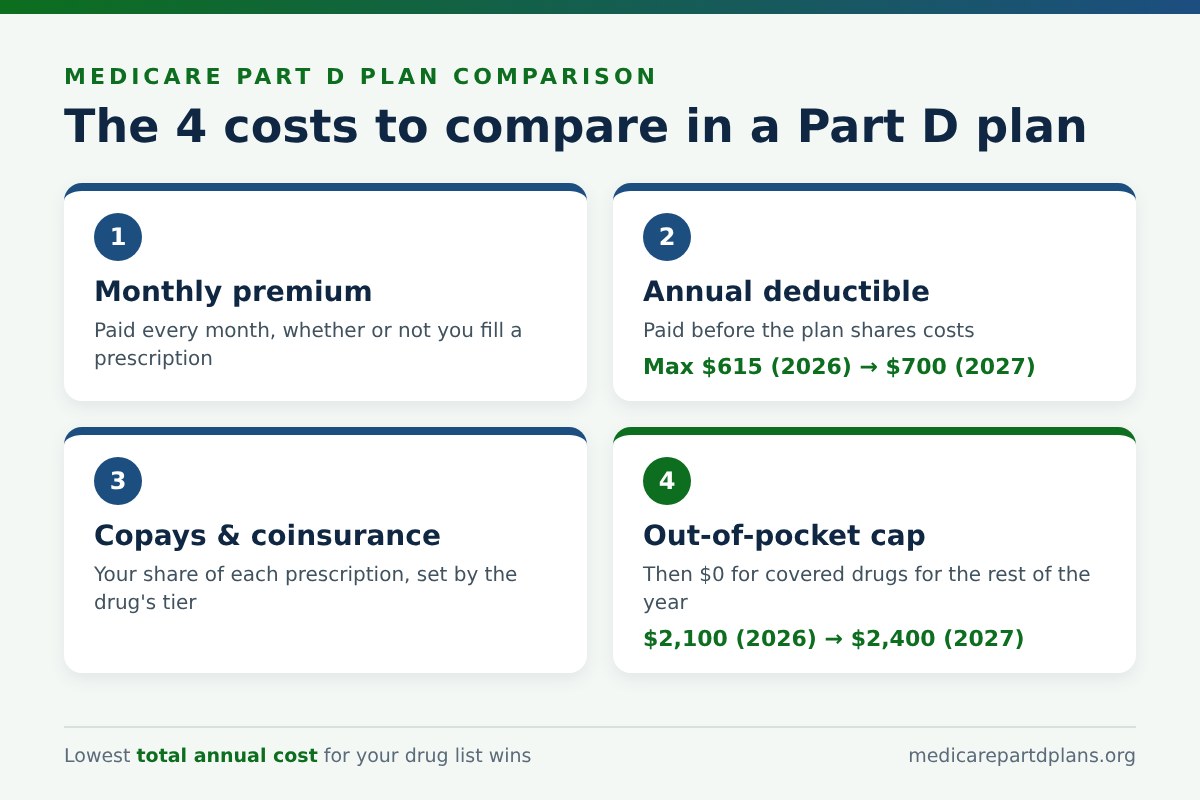
Every Part D plan charges you through the same four pieces. Compare all four together, using your own drug list, and the cheapest plan becomes clear. See our breakdown of Medicare Part D premiums for more on the first one.
1Monthly premium
What you pay to hold the plan, whether or not you fill a prescription. It is separate from your Part B premium. Higher earners also pay an IRMAA surcharge, billed by Social Security.
2Annual deductible
What you pay before the plan starts sharing costs. Medicare caps it at $615 in 2026 and $700 in 2027. Many plans charge less, and some waive it on low-tier generics.
3Copays and coinsurance
Your share of each prescription after the deductible. A copay is a flat dollar amount; coinsurance is a percentage, up to 25% in the standard benefit. Which one you pay depends on the drug’s tier and the pharmacy.
4Annual out-of-pocket cap
The most you can pay for covered drugs in a year: $2,100 in 2026 and $2,400 in 2027. Once you reach it, you pay nothing more for covered drugs until January.
| Part D figure | 2026 | 2027 |
|---|---|---|
| Maximum annual deductible | $615 | $700 |
| Annual out-of-pocket cap | $2,100 | $2,400 |
| Base beneficiary premium | $38.99 | $41.33 |
| Coverage gap (donut hole) | Eliminated | Eliminated |
Formularies and Drug Tiers
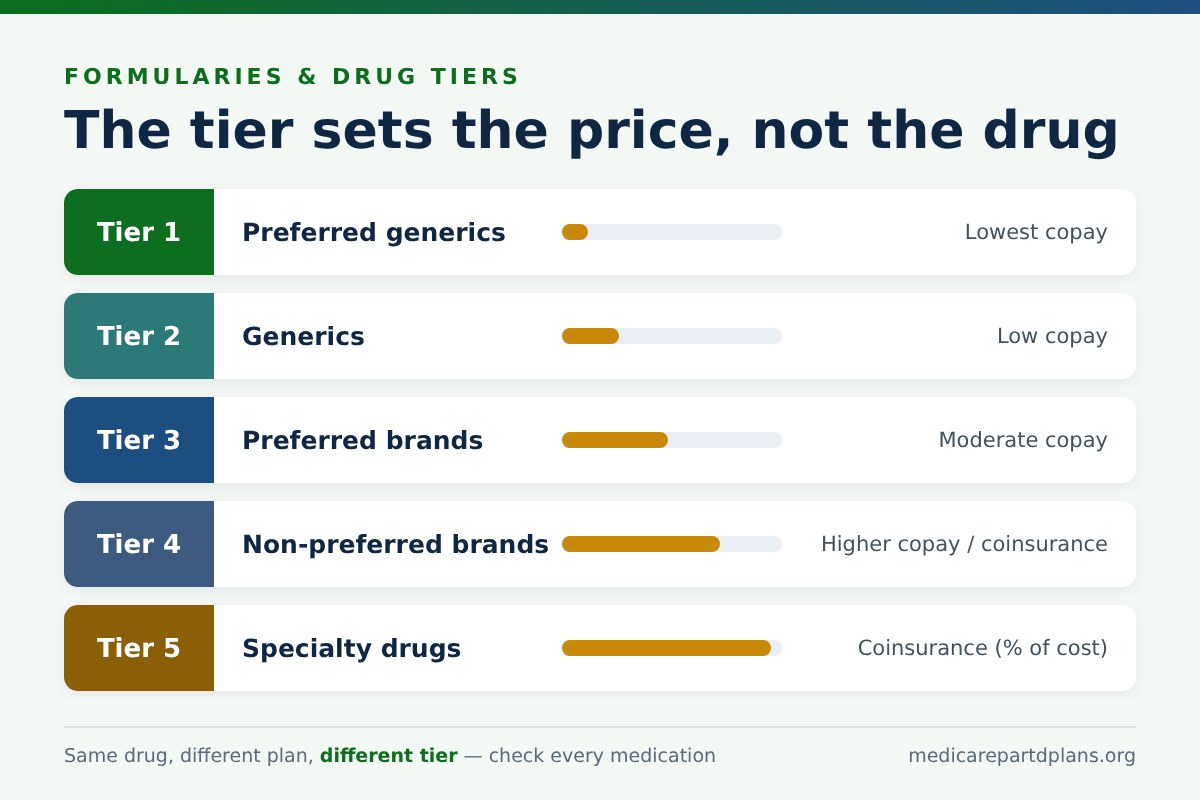
Each plan publishes a formulary, the list of drugs it covers, and sorts those drugs into tiers. The tier sets your price. The same drug can sit on tier 2 in one plan and tier 4 in another, so check every one of your medications against each plan you compare. Read more about formularies and drug tiers in Medicare Part D.
| Tier | What sits there | Your cost |
|---|---|---|
| Tier 1 | Preferred generics | Lowest copay, often a few dollars |
| Tier 2 | Generics | Low copay |
| Tier 3 | Preferred brand-name drugs | Moderate copay |
| Tier 4 | Non-preferred brand-name drugs | Higher copay or coinsurance |
| Tier 5 | Specialty drugs | Coinsurance, a percentage of the drug’s cost |
Pharmacies and Mail Order
Most plans have preferred pharmacies where your copays are lower. Same plan, same drug, different counter, different price. Out-of-network pharmacies usually cost more, and mail order is often cheapest for maintenance medications you take every month. Before you pick a plan, confirm the pharmacy you actually use is preferred in that plan.
The Coverage Gap Is Gone
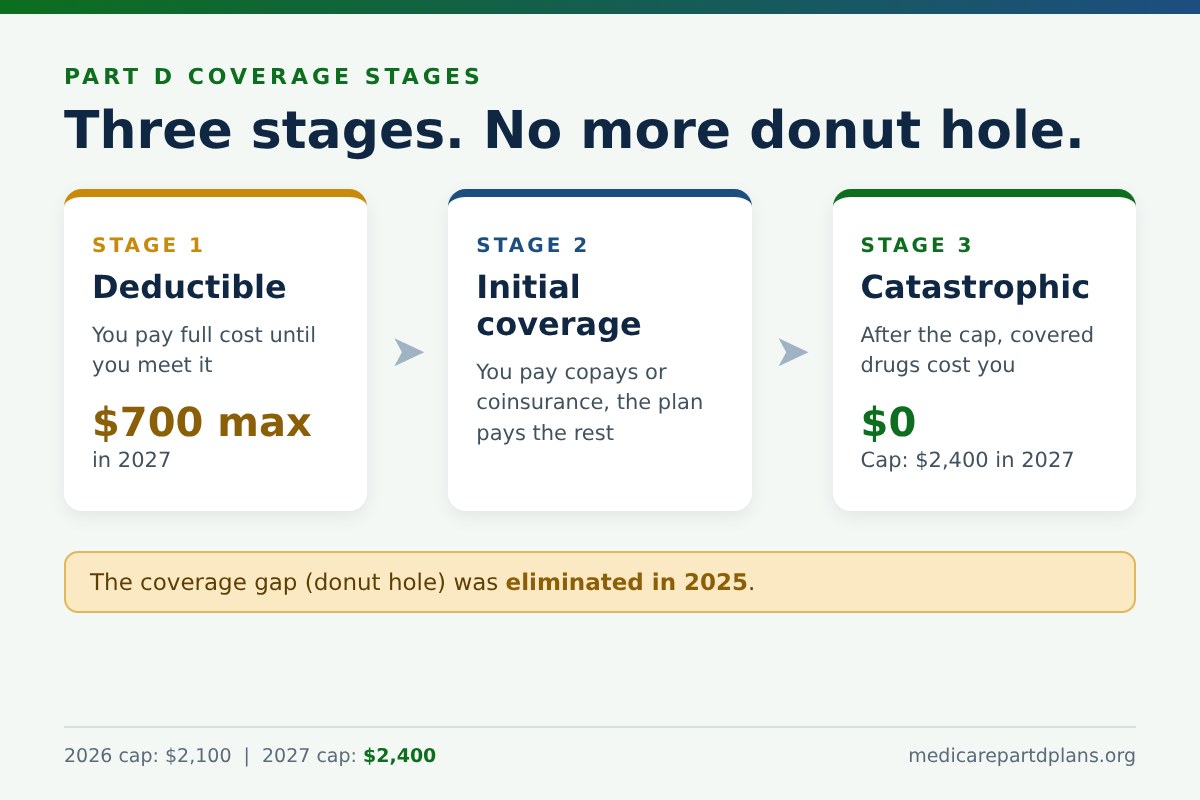 The coverage gap, also known as the donut hole, was eliminated in 2025. The Part D benefit now has three stages:
- Deductible: you pay full cost until you meet your plan’s deductible.
- Initial coverage: you pay copays or coinsurance and the plan pays the rest.
- Catastrophic coverage: once your out-of-pocket spending reaches the cap, $2,100 in 2026 and $2,400 in 2027, you pay $0 for covered drugs for the rest of the year.
Any guide still describing a coverage gap phase is out of date. If you take expensive medications, the cap is the number to watch, because it limits your worst-case year.
See plans in your area instantly!
Advertisement
Steps to Compare Medicare Part D Plans
Step 1
List every drug you take
Exact name, dosage and quantity per month. Without this list you are only comparing premiums, and premiums tell you little about what a plan will really cost you.
Step 2
Check each drug on the formulary
Confirm the plan covers each drug, then note its tier. A drug the plan does not cover costs full price, and that spending does not count toward your out-of-pocket cap.
Step 3
Add up the total annual cost
Premium times twelve, plus the deductible, plus your estimated copays for the year. A $0 premium plan that puts one of your drugs on tier 4 can cost more than a plan with a higher premium.
Step 4
Confirm your pharmacy is preferred
Preferred pharmacies charge lower copays. Check that the pharmacy you use is preferred in the plan, and look at mail order for drugs you take every month.
Step 5
Review the plan documents, then enroll
Read the Summary of Benefits and the formulary for your top choice before you enroll. You can also compare Medicare Part D plans by state to see what is offered where you live.
Want help comparing?
Enter your ZIP code on this page to see the plans available where you live, or call a licensed insurance agent at 1-866-930-4039, TTY 711, Monday to Friday, 8 am to 8 pm EST. An agent can check your drug list against the plans in your area at no cost to you.
When You Can Enroll or Switch
Part D has set enrollment windows. Outside them, you can only join or switch if you qualify for a special period.
| Enrollment period | When | What you can do |
|---|---|---|
| Annual Enrollment Period | October 15 to December 7 every year | Join, switch or drop a Part D plan. Changes start January 1. |
| Initial Enrollment Period | 7 months around your 65th birthday: 3 months before, your birthday month, and 3 months after | Join your first Part D plan without a penalty |
| Special Enrollment Period | After a qualifying life event | Join or switch outside the usual windows, for example after a move or losing other drug coverage |
See our guide to the Annual Enrollment Period for Medicare Part D for key dates and what to review before you switch.
Find a Plan and Enroll Online Yourself!
Advertisement
Summary
The right Medicare Part D plan is the one that covers all of your drugs at the lowest total cost for the year, at a pharmacy you can use. Start with your drug list, check each plan’s formulary and tiers, add up premium, deductible and copays, and confirm your pharmacy is preferred. Then review the plan documents and enroll during the right window.
For 2027, costs are rising, with a $700 maximum deductible and a $2,400 out-of-pocket cap, so it pays to compare during this year’s Annual Enrollment Period rather than letting your plan renew automatically. See Medicare Part D plans 2027 and the full Medicare Part D plans guide.
Frequently Asked Questions
➤ What are the two main types of Medicare Part D plans?
Standalone Prescription Drug Plans (PDPs), which you add to Original Medicare, and Medicare Advantage Prescription Drug plans (MA-PDs), which include drug coverage inside a Medicare Advantage plan. You can have one or the other, not both.
➤ How do I find a Medicare Part D plan that covers my medications?
List every drug you take with its dosage, then enter your ZIP code on this page to see the plans in your area and check each drug against each plan’s formulary. A licensed agent at 1-866-930-4039 can also run your drug list for you.
➤ Is there still a coverage gap in Medicare Part D?
No. The coverage gap, or donut hole, was eliminated in 2025. Once your out-of-pocket spending reaches the annual cap, $2,100
➤ What is the cheapest way to compare Part D plans?
Compare total annual cost, not premium. Add the premium for twelve months, the deductible, and your estimated copays for each of your drugs. The plan with the lowest total for your own drug list is the cheapest plan for you.
➤ When is the Annual Enrollment Period for Medicare Part D?
October 15 to December 7 every year. Changes you make take effect January 1. For 2027 coverage, that window is October 15 to December 7,
➤ What is changing in Medicare Part D for 2027?
The maximum deductible rises from $615 to $700, the annual out-of-pocket cap rises from $2,100 to $2,400, and the base beneficiary premium rises from $38.99 to $41.33. The temporary premium stabilization subsidy also ends on December 31,
➤ Why should I review plan documents before enrolling?
The Summary of Benefits and formulary show exactly which drugs are covered, on which tier, at which pharmacies, and any limits such as prior authorization or quantity limits. Checking them before you enroll prevents surprises at the pharmacy counter.
Begin Choosing your plan
Advertisement
ZRN Health & Financial Services, LLC, a Texas limited liability company.