Find a Medicare Part D prescription drug plan
Medicare Part D
Prescription Drug Coverage 2027
Medicare Part D Plans 2027
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated September 16, 2026
Medicare Part D plans for 2027 cost more than they did this year, and the increases are not evenly spread. The standard deductible rises to $700. The annual out-of-pocket cap rises to $2,400. And two temporary price protections that held standalone drug plan premiums down for the last two years expire on December 31, 2026.
That last one is the part almost nobody is talking about, and it is the reason renewing your current plan without checking is a more expensive decision this year than it was last year. This page walks through every 2027 number that has been confirmed, what it means for what you actually pay at the pharmacy, and how to compare plans before enrollment closes on December 7.
Key Takeaways
- The standard Medicare Part D deductible rises to $700 in 2027, up from $615 — a 13.8% increase.
- The annual out-of-pocket cap rises to $2,400, up from $2,100. Once you reach it, covered drugs cost you nothing for the rest of the year.
- The Part D base beneficiary premium rises to $41.33, up from $38.99.
- The Premium Stabilization Demonstration ends December 31, 2026. The $10 monthly subsidy and the $50 cap on premium increases both disappear.
- Enrollment for 2027 coverage runs October 15 through December 7, 2026.
What Is Changing in Medicare Part D for 2027
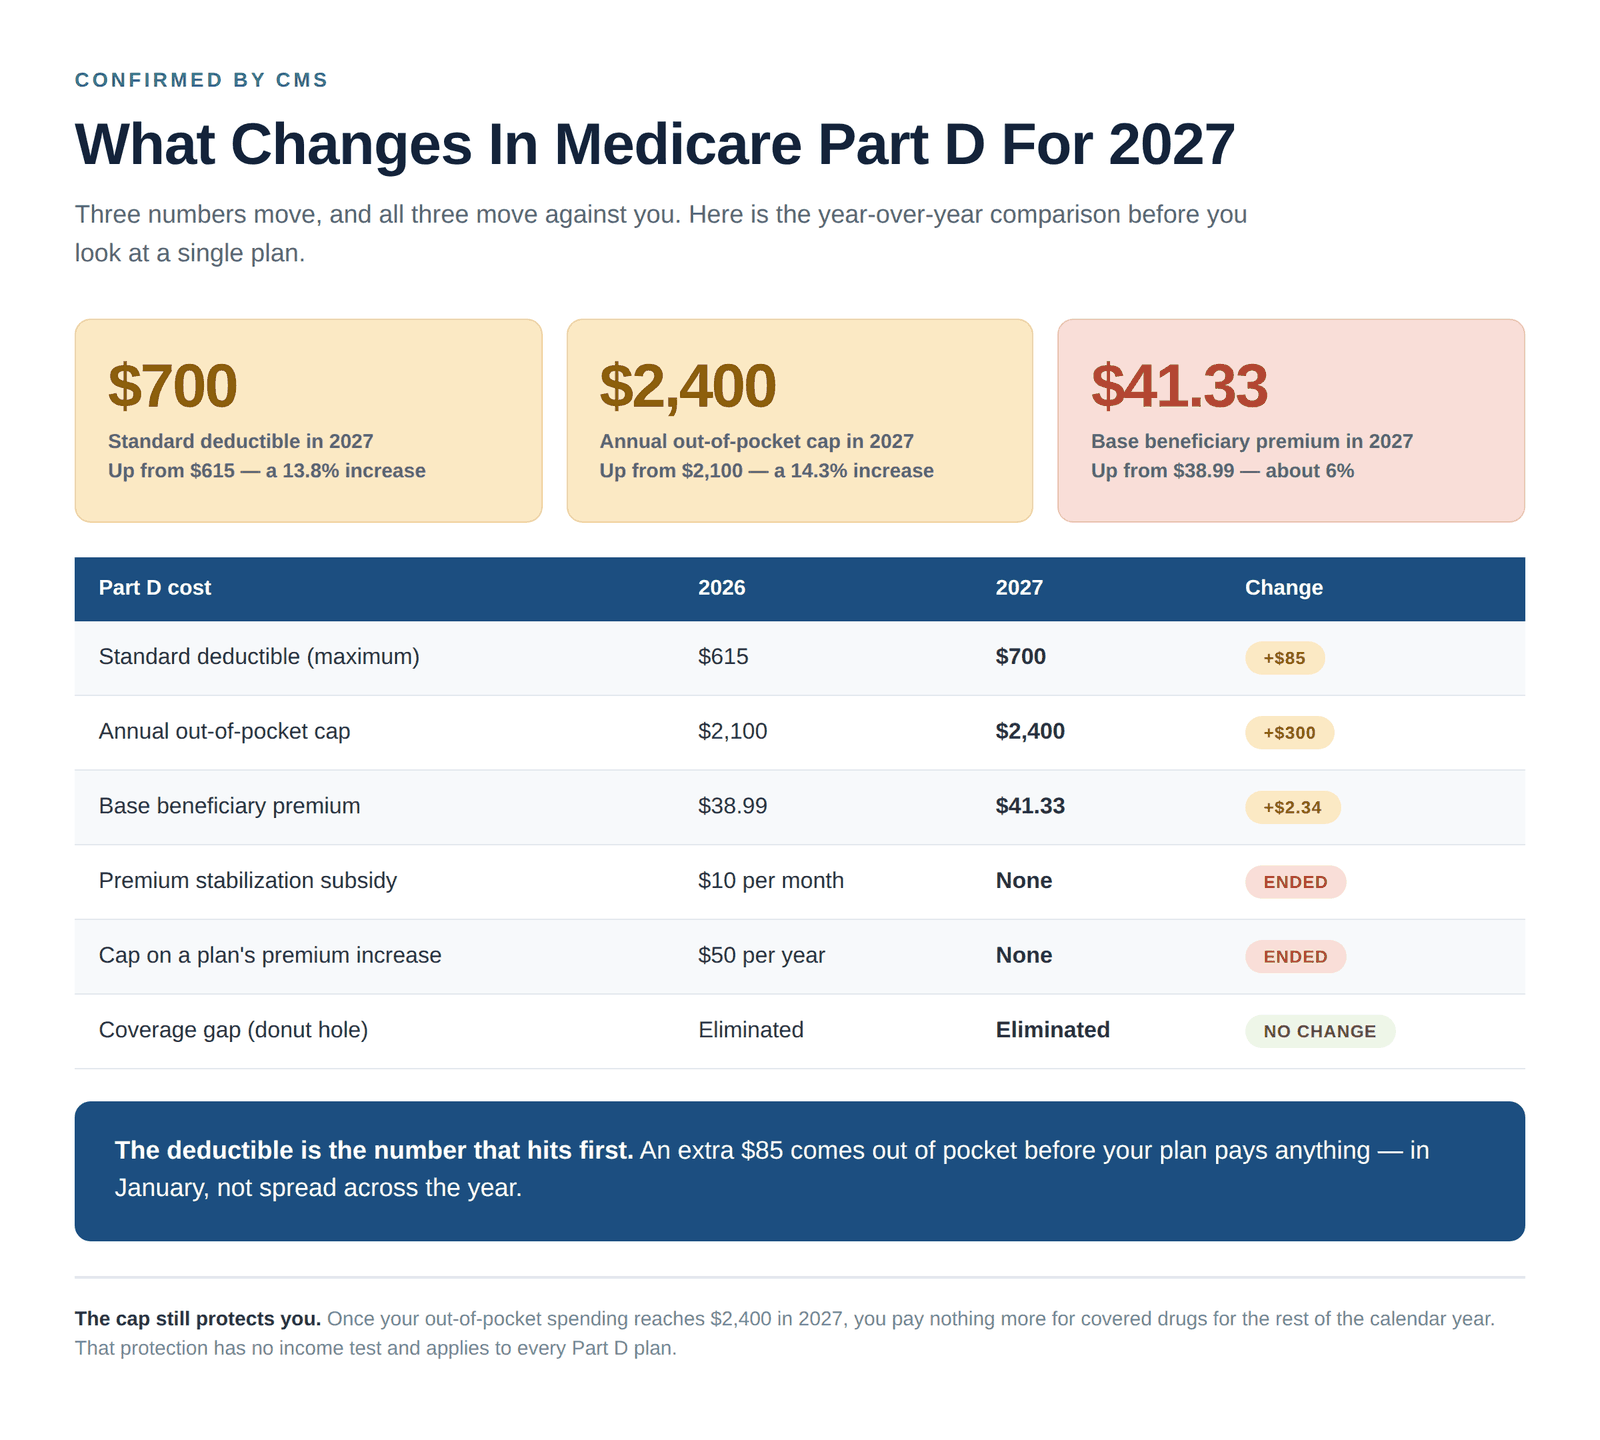
Three numbers move for 2027, and all three move against you. Here is the year-over-year comparison, straight from the CMS parameters.
| Part D cost | 2026 | 2027 | Change |
|---|---|---|---|
| $Standard deductible (maximum) | $615 | $700 | +$85 |
| ⚑Annual out-of-pocket cap | $2,100 | $2,400 | +$300 |
| ◆Base beneficiary premium | $38.99 | $41.33 | +$2.34 |
| ✗Premium stabilization subsidy | $10 per month | None | Ended |
| ✗Cap on a plan’s premium increase | $50 per year | None | Ended |
| ✓Coverage gap (donut hole) | Eliminated | Eliminated | No change |
The deductible is the number that hits first and hardest. That extra $85 comes out of your pocket in January, before your plan pays anything, not spread across twelve months. If you take several maintenance medications you will clear it quickly. If you take one generic, you may never reach it at all — which is exactly why the right plan for your neighbor is often the wrong plan for you.
Why Medicare Part D Premiums Are Rising in 2027
For the last two years, standalone Prescription Drug Plan premiums have been artificially low. Not because the plans got cheaper, but because CMS was propping them up through the Part D Premium Stabilization Demonstration — a temporary program created to keep premiums from spiking while the Inflation Reduction Act redesigned the benefit.
On July 28, 2026, CMS announced the demonstration will conclude on December 31, 2026, one year earlier than originally scheduled. CMS says plan sponsors now have enough experience pricing the redesigned benefit that the subsidy is no longer necessary.
Two Medicare Part D Price Protections End in 2026
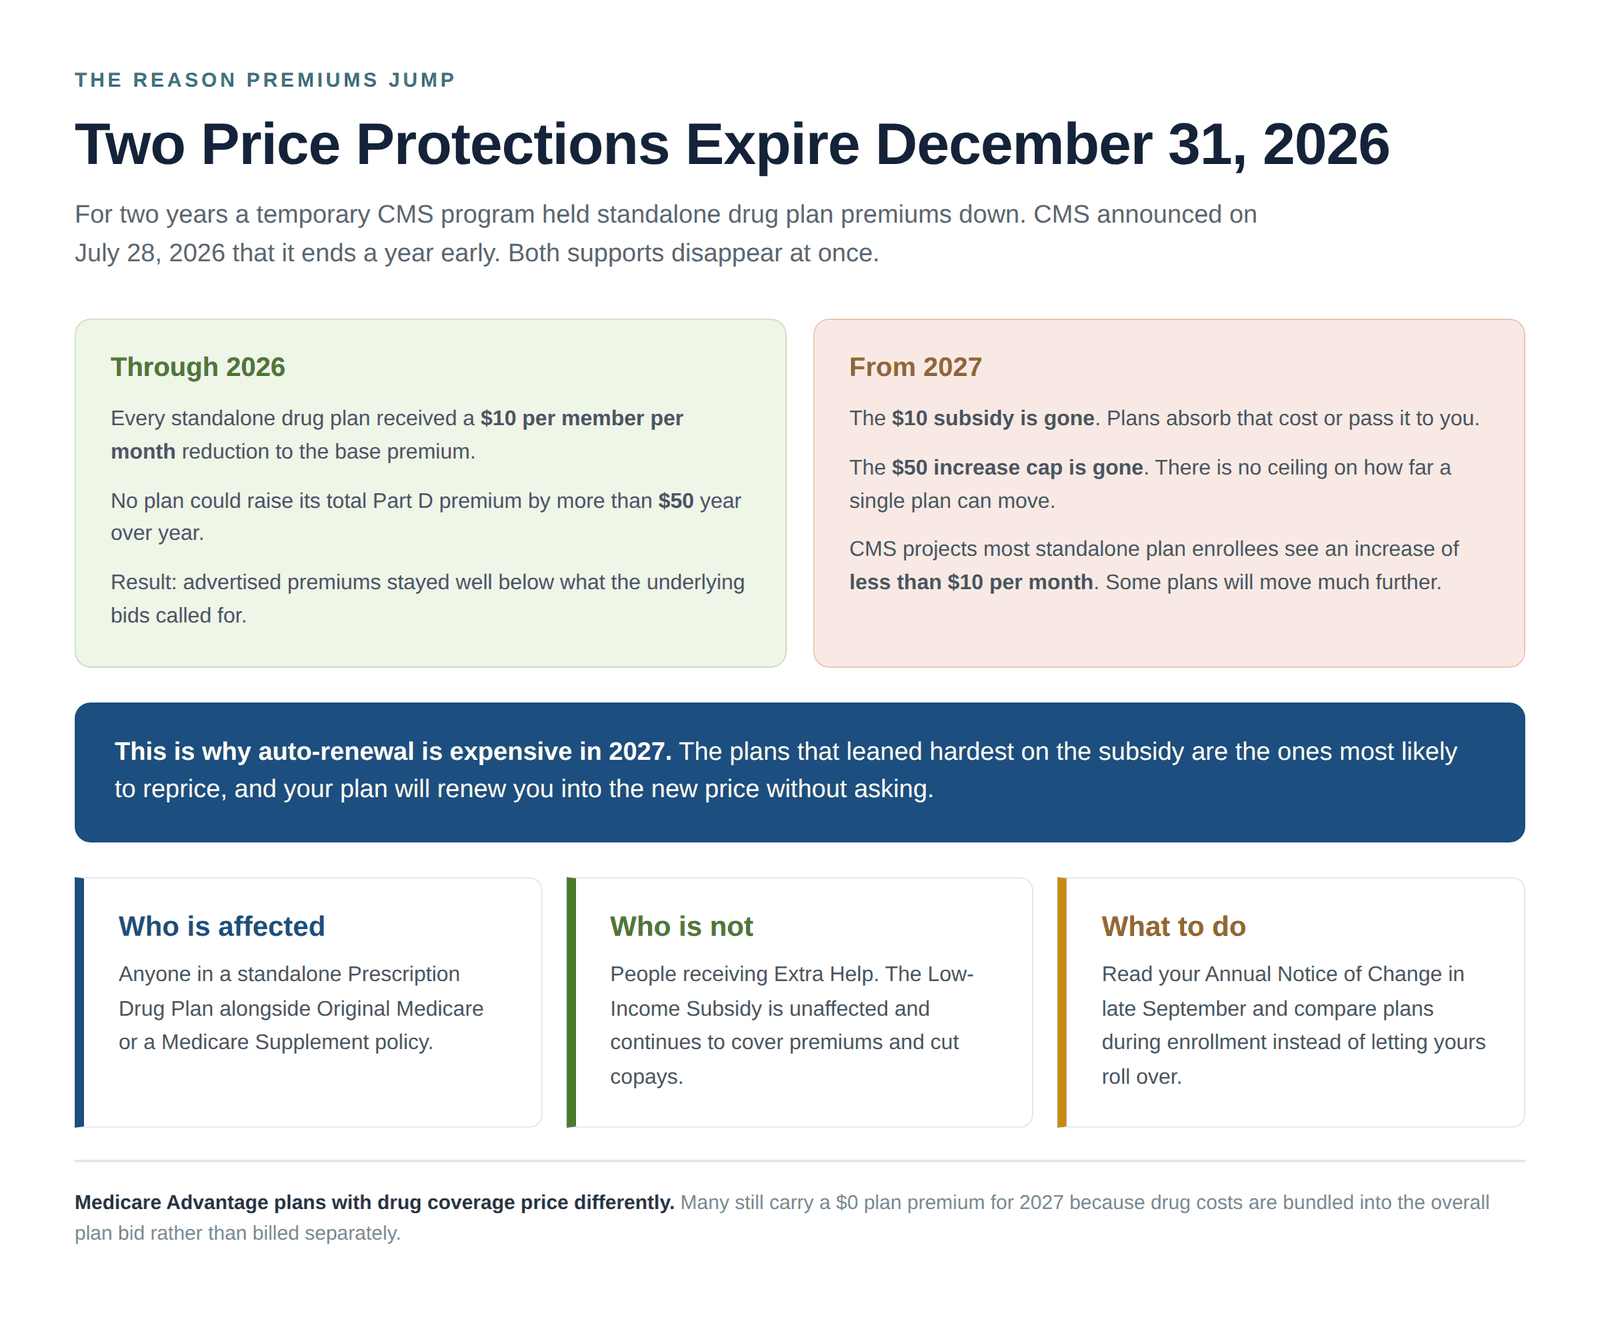
Protection 1 gone
The $10 monthly subsidy
Every standalone drug plan received a uniform $10 per member per month reduction to the base beneficiary premium in 2026, down from $15 in 2025. From 2027 that reduction is zero. Plans either absorb the difference or pass it through to your premium.
Protection 2 gone
The $50 increase ceiling
No plan was allowed to raise its total Part D premium by more than $50 year over year in 2026. That ceiling is gone for 2027. There is no longer a limit on how far a single plan can move its price in one year.
CMS projects that most standalone plan enrollees will see individual premium increases of less than $10 per month. That is the average, and averages hide the outliers. The plans that leaned hardest on the subsidy to advertise a low headline premium are the ones most likely to reprice sharply, and your plan will renew you into whatever the new number is without asking your permission.
Doing nothing is the expensive choice this year
If you make no change by December 7, your plan rolls you into its 2027 version automatically — at the 2027 price, with the 2027 formulary and the 2027 pharmacy network. In a normal year that is a reasonable default. In 2027, with both price protections removed at once, it is a gamble.
Compare Medicare Part D Plans for 2027
Advertisement
How Medicare Part D Costs Work in 2027
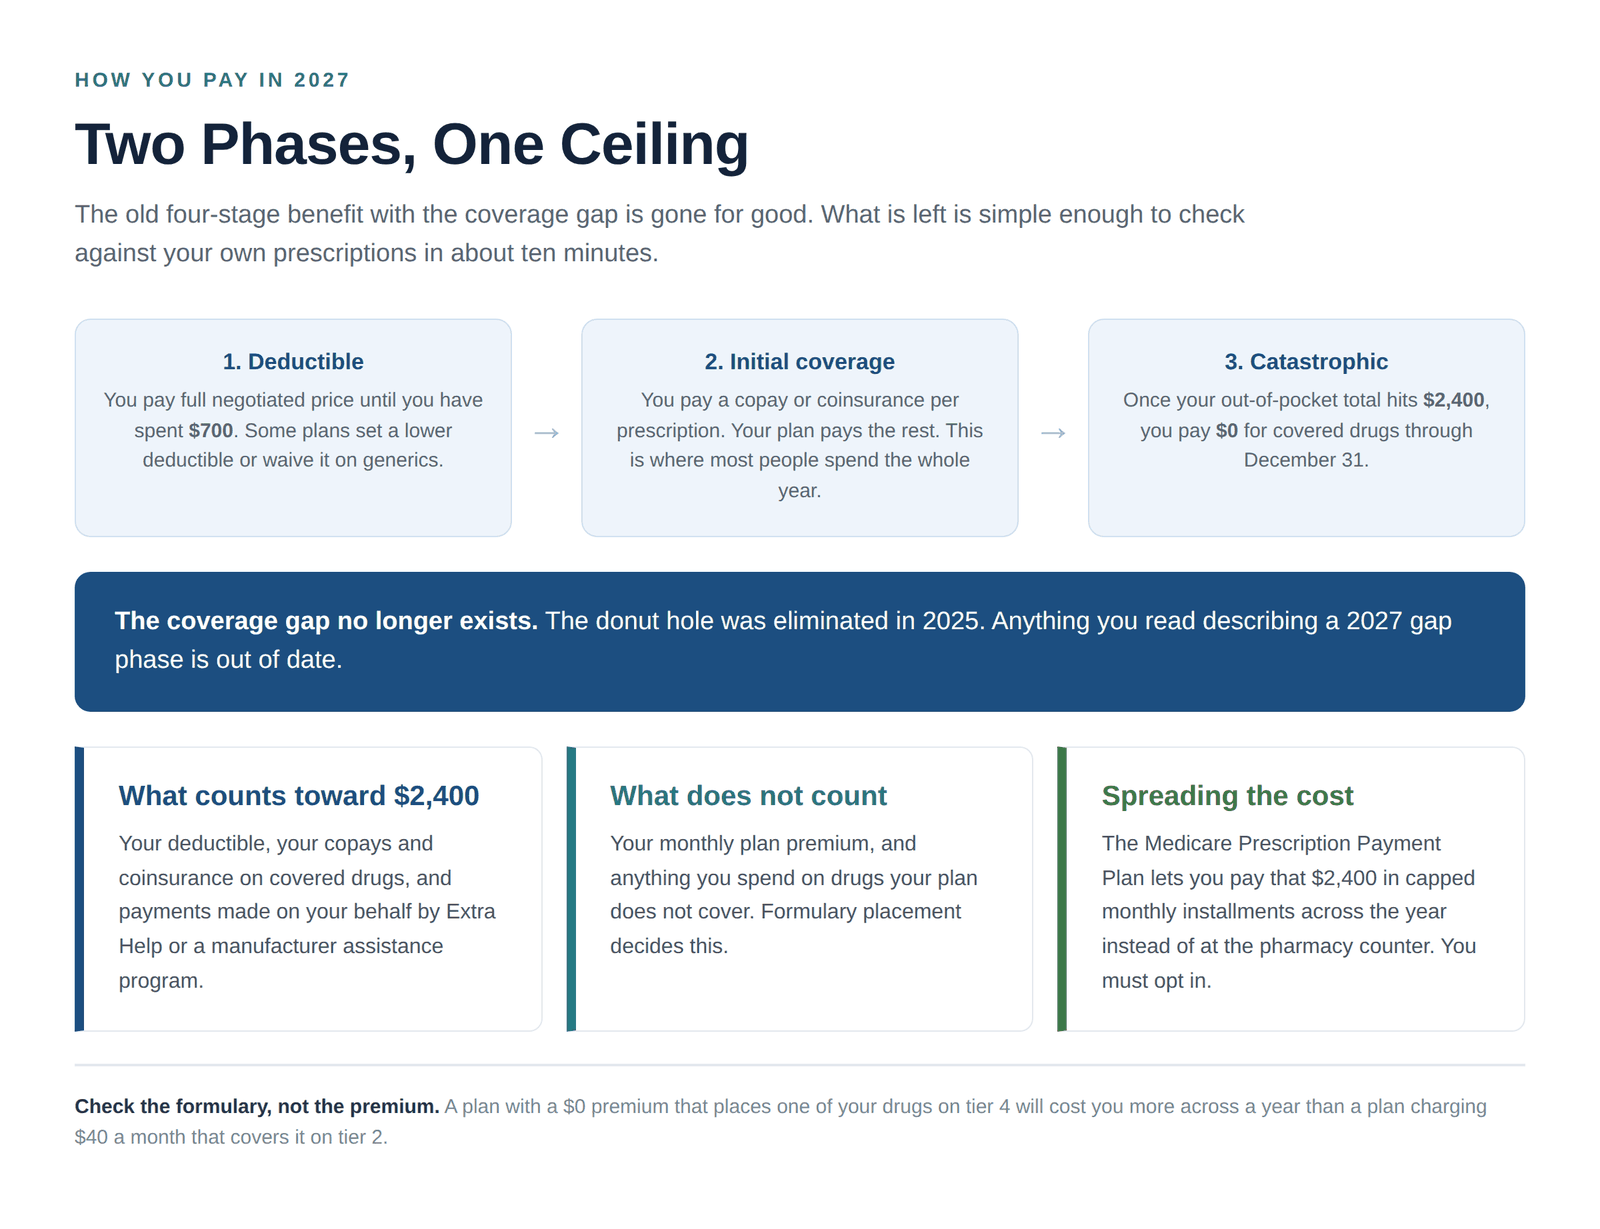
The old four-stage benefit with the coverage gap is gone for good. The donut hole was eliminated in 2025 and it is not coming back. What remains is simple enough to check against your own prescription list in about ten minutes.
See plans in your area instantly!
Advertisement
The Three Medicare Part D Coverage Phases in 2027
1The deductible phase
You pay the full negotiated price for your drugs until you have spent $700. Not every plan charges the full deductible — some set a lower amount, and many waive it entirely on tier 1 and tier 2 generics. That single design choice can be worth several hundred dollars a year depending on what you take.
2The initial coverage phase
Once the deductible is satisfied, you pay a copay or a percentage per prescription and your plan pays the rest. Most people spend the entire year in this phase and never leave it. What you pay here is driven almost entirely by which tier your specific drugs sit on, which is why two plans with identical premiums can produce wildly different annual costs.
3The catastrophic phase
The moment your out-of-pocket spending reaches $2,400, you pay $0 for covered drugs for the remainder of the calendar year. There is no income test and no application. This protection applies to every Part D plan sold, and for anyone on a high-cost specialty medication it is the single most valuable feature of the modern benefit.
Your deductible, copays and coinsurance on covered drugs all count toward that $2,400, and so do payments made on your behalf through Extra Help or a manufacturer assistance program. What does not count is your monthly plan premium, and anything you spend on a drug your plan does not cover at all. That second exclusion is why checking the formulary matters more than checking the premium. For a closer look at how the deductible works in practice, see our breakdown of Medicare Part D deductibles.
Medicare Part D Enrollment Dates for 2027
The Annual Enrollment Period for 2027 coverage runs from October 15 to December 7, 2026. Anything you change during that window takes effect January 1, 2027. If you make more than one change, the last one on file before December 7 is the one that counts.
| Window | Dates | What you can do |
|---|---|---|
| Annual Enrollment Period | Oct 15 – Dec 7, 2026 | Join, switch or drop a Part D plan. Coverage begins January 1, 2027. |
| Medicare Advantage Open Enrollment | Jan 1 – Mar 31, 2027 | Switch Medicare Advantage plans or return to Original Medicare with a drug plan. Not open to standalone PDP switching. |
| Initial Enrollment Period | 7 months around your 65th birthday | Enroll in Part D for the first time without a late penalty. |
| Special Enrollment Period | Varies | Triggered by a move, loss of creditable coverage, or your plan leaving your area. |
Your Annual Notice of Change arrives by late September 2026. It lists every way your current plan is different next year — premium, deductible, formulary, pharmacy network. It is the single most useful piece of mail you will receive all year and most people throw it away unopened.
How to Choose a Medicare Part D Plan for 2027
Step 1
Write down every drug you take
Exact name, exact dosage, exact quantity per month. This list is the only thing that makes a comparison meaningful. Without it you are comparing premiums, and premiums are the least important number on the page.
Step 2
Read your Annual Notice of Change
Compare the 2027 premium, deductible and tier placement against what you are paying now. If a drug moved up a tier or picked up a prior authorization requirement, your costs change even if the premium did not.
Step 3
Compare total annual cost, not premium
Premium times twelve, plus deductible, plus your estimated copays for the year. A $0 premium plan that puts one of your drugs on tier 4 routinely costs more across a year than a $40 plan that covers it on tier 2. Run the total on your own Medicare Part D plan comparison before you decide.
Step 4
Check your pharmacy is preferred
Most plans have a preferred pharmacy tier where cost sharing is meaningfully lower. The same plan, the same drug, a different counter, and the price changes. Confirm your pharmacy before enrolling rather than after.
Step 5
Enroll before December 7
There is no advantage to waiting and no penalty for deciding early. Coverage starts January 1, 2027 either way. The only thing waiting does is increase the chance you miss the deadline entirely.
See plans in your area instantly!
Advertisement
Which Carriers Offer Medicare Part D Plans in 2027
Plan availability, pricing and formularies vary by county and are set each year, so treat the list below as a shortlist to price against your own drug list rather than a ranking. Specific 2027 benefits depend on the plan and your area, and not every carrier offers every plan everywhere.
| Carrier | What to look at |
|---|---|
| Humana | Broad standalone PDP availability and a large preferred cost-sharing pharmacy network in most markets. |
| Cigna Healthcare | Competitive premiums in many regions, with mail-order options that can lower cost on maintenance drugs. |
| Aetna / SilverScript | One of the largest standalone PDP books in the country, with wide pharmacy access. |
| UnitedHealthcare | Extensive formularies and preferred pharmacy pricing at major retail chains in most areas. |
| Blue Cross Blue Shield | Availability and pricing vary considerably by state because each Blue plan is licensed regionally. |
Carrier reputation is a starting point, not an answer. The plan that wins for you is the one that covers your specific drugs at the lowest total annual cost at a pharmacy you can actually get to. If you want a shortlist weighted by CMS star ratings, start with our best rated Medicare Part D plans, then price them against your own list.
Extra Help With Medicare Part D Costs in 2027
The Low-Income Subsidy, commonly called Extra Help, is unaffected by the premium stabilization demonstration ending. If you qualify, it can cover your plan premium entirely, eliminate your deductible, and reduce your copays to a few dollars per prescription. It is the single largest cost reduction available in Part D and a significant number of people who qualify never apply.
Do not rule yourself out on assets
Countable resources include bank accounts, stocks and bonds. They do not include your home, your vehicle, your personal belongings or a burial plot. People routinely assume their savings disqualify them when they do not. Apply through the Social Security Administration and let them make the determination.
Spreading Your 2027 Drug Costs Across the Year
The Medicare Prescription Payment Plan lets you spread your out-of-pocket drug costs into capped monthly payments across the calendar year instead of paying large amounts at the pharmacy counter. It does not reduce what you owe in total — you still pay up to $2,400 — but it smooths the timing, which matters most to people who would otherwise face the whole deductible plus heavy copays in January and February.
Participation is voluntary and you must opt in through your Part D plan. It is worth considering if you take a high-cost specialty medication and expect to hit the cap early in the year. It is generally not worth the paperwork if your annual drug spend is modest. You can review what Part D covers before deciding on our guide to what Part D Medicare covers.
Where to Compare Medicare Part D Plans for 2027
The official Medicare Plan Finder at Medicare.gov lets you enter your drug list and your ZIP code and returns every plan available to you with an estimated annual cost. It is free, it is unbiased, and it is the only tool that prices your actual medications. For the 2027 program rules themselves, the CMS Part D parameters fact sheet is the primary source, and Social Security handles Extra Help applications.
If you would rather not do it alone, a licensed agent can run the same comparison with you at no cost. You can also compare Medicare Part D plans and enroll online yourself in a few minutes.
For more background, review the 2026 Medicare Part D plans to see how this year’s structure compares, browse every option under Medicare Part D plans, or read more about Medicare Part D prescription drug plans.
Frequently Asked Questions About Medicare Part D Plans 2027
➤ What is the Medicare Part D deductible for 2027?
The standard Medicare Part D deductible for 2027 is $700, up from $615 in 2026. That is the maximum a plan may charge. Individual plans can set a lower deductible or waive it entirely on certain generic tiers, so check the plan’s own figure rather than assuming the standard amount.
➤ What is the out-of-pocket maximum for Medicare Part D plans 2027?
The annual out-of-pocket cap for 2027 is $2,400, up from $2,100 in 2026. Once your out-of-pocket spending on covered drugs reaches $2,400, you pay nothing more for those drugs for the rest of the calendar year. There is no income test and no application required.
➤ When can I enroll in Medicare Part D plans for 2027?
The Annual Enrollment Period runs October 15 through December 7, 2026. Any plan you join, switch to or drop during that window takes effect January 1, 2027. If you submit more than one change, the last one on file before December 7 is the one that applies.
➤ Why are Medicare Part D premiums going up in 2027?
Two temporary price protections expire on December 31, 2026. The Part D Premium Stabilization Demonstration gave every standalone drug plan a $10 per member per month premium subsidy and capped any single plan’s premium increase at $50 per year. CMS announced on July 28, 2026 that the program ends a year early, so both supports disappear at once for 2027.
➤ How much will my Medicare Part D premium increase in 2027?
CMS projects that most standalone Prescription Drug Plan enrollees will see individual premium increases of less than $10 per month. That is an average across the market. With the $50 increase ceiling removed, individual plans that relied heavily on the subsidy may move considerably further, which is why comparing rather than auto-renewing matters this year.
➤ Is there still a donut hole in Medicare Part D plans 2027?
No. The coverage gap, commonly called the donut hole, was eliminated in 2025 and does not exist in 2027. The benefit now runs from the deductible through an initial coverage phase and into catastrophic coverage once you reach the $2,400 cap. Any article describing a 2027 coverage gap is out of date.
➤ What happens if I do nothing before December 7?
Your current plan will renew you automatically into its 2027 version at the 2027 premium, with the 2027 formulary and the 2027 pharmacy network. You will not be asked to approve the new price. Because both premium protections end this year, auto-renewal carries more cost risk for 2027 than it has in previous years.
➤ Can I get help paying for Medicare Part D plans in 2027?
Yes. The Low-Income Subsidy, also called Extra Help, can cover your plan premium, eliminate your deductible and reduce copays to a few dollars per prescription. It is unaffected by the premium stabilization demonstration ending. Your home, vehicle, personal belongings and burial plot do not count as resources, so apply through Social Security rather than assuming you are ineligible.
➤ Should I choose a standalone Part D plan or a Medicare Advantage plan with drug coverage?
It depends on how you want the rest of your Medicare structured. A standalone Prescription Drug Plan is the right choice if you are keeping Original Medicare, and it is required if you hold a Medicare Supplement policy. A Medicare Advantage plan with drug coverage bundles everything into one plan and often carries a $0 plan premium, but it comes with a network. Compare total annual cost either way rather than the monthly premium alone.